A few years ago, a queue at the till was the clearest measure of a restaurant’s success. Today, that queue has largely moved elsewhere. Now it’s in an app, a drive-thru lane, or a delivery rider’s route. For South Africa’s restaurant and quick-service restaurant (QSR) sector, this isn’t a passing trend accelerated by convenience; it’s a foundational rewrite of what the business actually is.
The critical question for franchisors and franchisees is no longer simply how to manage rising costs. It’s how to build a business model that is fit for a customer who may never set foot in the store.
For Nedbank, which works closely with businesses across South Africa’s franchise ecosystem, this shift is particularly significant. The bank’s experience in franchising provides insight into how changes in consumer behaviour are translating into decisions around store formats, technology, capital investment, energy resilience and expansion.
South Africa’s QSR and Food Landscape
Globally, digital ordering now accounts for more than 40% of transactions at major chains, and off-premise formats – drive-thru, delivery and takeaway combined – already generate over 70% of revenue at leading QSR brands.
South Africa is following the same trajectory. Delivery platforms have moved from novelty to infrastructure: Mr D Food and Uber Eats between them account for more than half of the country’s food delivery market, and Uber Eats alone reports that its South African platform injected R17 billion into the economy in 2025, saving users a combined 12,7 million hours through the convenience of not having to leave home or queue.
For restaurant operators, the implication is clear: convenience is no longer an additional sales channel. It is increasingly part of the core operating model.
Compact, delivery-optimised store formats, fuel-station forecourt drive-thrus, and cloud/dark kitchens built solely to service delivery orders are no longer experimental. They’re becoming standard frameworks for chains competing on speed and reach.
Cloud kitchens are now the second-fastest-growing foodservice format in South Africa by outlet count.
From a franchising perspective, this evolution has an important financial implication: the format of the business increasingly determines the format of the investment.
A franchisee opening a compact delivery-led site has different capital requirements from one investing in a traditional restaurant. A drive-thru requires different infrastructure from a high-street outlet, while a multi-site operator may need to invest simultaneously in technology, refurbishment, renewable energy and working capital.
Understanding those differences is where sector expertise becomes particularly valuable.
Nedbank’s approach to franchising is built around this principle: financing decisions need to be informed by an understanding of the business model, its sector and its growth ambitions – rather than treating every business as though it has the same requirements.
Margin Under Pressure, Value Is Non-negotiable
Convenience may be an increasingly important driver, but consumers still expect value.
While general food inflation in South Africa has eased, eating out is getting more expensive even as grocery inflation cools. Filling that gap sits squarely on operators, who are absorbing rising input, labour, delivery-platform and technology costs while trying to hold the line on price for consumers who are conscious of every Rand.
Although value meals and combos priced between R50 and R100 are performing strongly, particularly among lower- and middle-income diners, this creates one of the sector’s central tensions: operators need to protect margins while continuing to offer the affordability and convenience customers expect.
For franchise businesses, that tension cannot be addressed through pricing alone. It requires a more intelligent understanding of the economics of each channel.
Which products generate profitable volume? Which stores justify expansion? Does a new format improve efficiency enough to warrant the capital investment? How much does delivery contribute to revenue once associated costs are accounted for? Where can technology reduce friction or improve throughput?
These are commercial decisions, but they are also financial decisions.
This is why Nedbank’s role in the franchise sector extends beyond providing funding. Its specialist franchise bankers engage with the economics of the business to understand what’s driving performance and where investment can create greater efficiency and resilience.
The objective is not simply to fund growth; it’s to help businesses make informed investment decisions that support sustainable growth.
Data as a Competitive Advantage
As the restaurant model becomes more complex, data is increasingly critical to how franchise businesses make decisions.
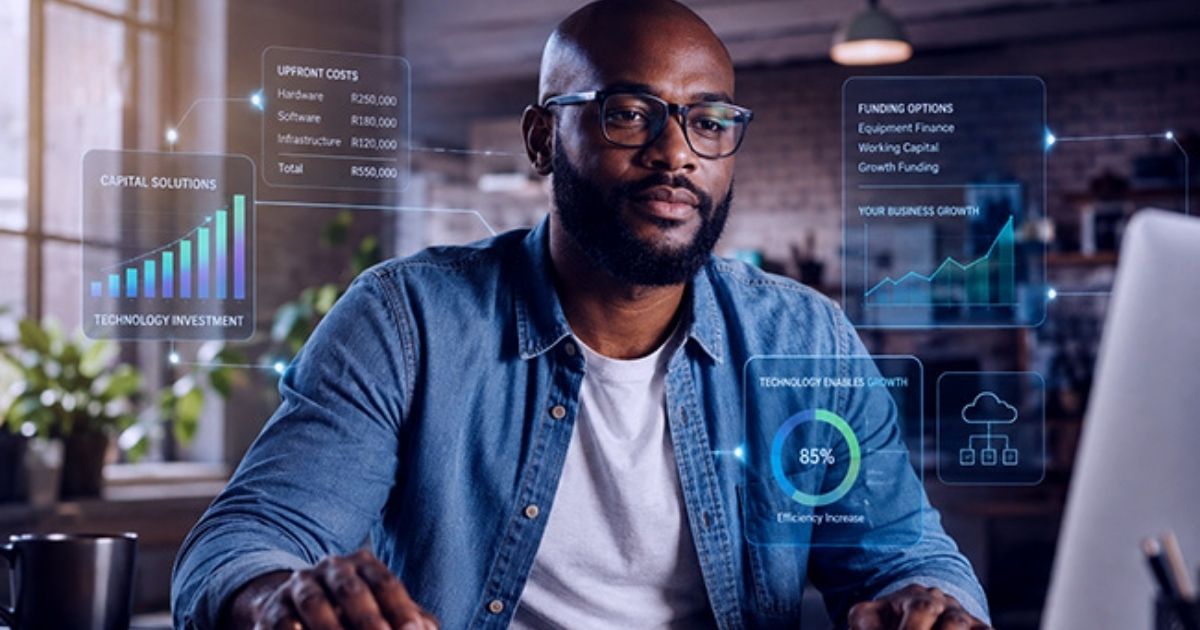
The operators pulling ahead are treating data and technology as growth levers rather than back-office functions. They are leveraging information on customer behaviour, product performance, store economics and channel profitability to inform decisions about where to open, what to sell and how to encourage repeat visits.
For a multi-site franchisee, this intelligence can make the difference between simply adding stores and building a scalable business. It can also change the financing conversation.
A business with a clear understanding of its unit economics is better placed to assess the potential return on a refurbishment, new site, technology investment or renewable energy installation. It can identify where capital is needed, what problem that capital is solving and how the investment supports the wider growth strategy.
This aligns with Nedbank’s broader approach to commercial banking: helping businesses become more intelligent by turning information into better decision-making.
Resilience Is Part Of The Growth Strategy
Structural changes are forcing franchise businesses to think differently about resilience.
Energy is a good example. For restaurants and QSRs, uninterrupted operations are directly linked to revenue. Investment in renewable energy is therefore not simply an environmental consideration; it can become a business continuity and competitiveness decision.
The same applies to technology and supply chains. A digital ordering system can improve throughput, and a diversified fulfilment model can give a business greater flexibility when customer behaviour changes.
For Nedbank, this is an important distinction. Resilience should not be viewed simply as protection against risk. The right investments can create a competitive advantage.
That perspective is particularly relevant to established SMEs and multi-site franchise operators considering their next phase of growth. The question is not only what a business needs to spend, but also how that investment can make the business more efficient, adaptable and sustainable over the longer term.
Growth Requires More than Capital
The evolving QSR landscape is also changing what businesses need from their banking partners. Franchisors are making decisions about expansion strategies and the resilience of their franchise networks, while franchisees are assessing new sites, technology investments and renewable energy. Each decision has implications across the wider franchise ecosystem. This makes sector knowledge increasingly important.
Nedbank’s franchising specialists focus specifically on franchise portfolios, supported by a credit approach designed around the nuances of the franchise model rather than generic small-business criteria. This approach supports a range of business requirements, including new stores, revamps and refurbishments, business resale transactions and renewable energy investment, alongside transacting, insurance and cash-flow solutions suited to multi-site operations.
But the value of that relationship extends beyond the financing itself. It’s about understanding why an investment is being made, how it fits into the franchise model and what it is intended to achieve.
The future of South Africa’s QSR sector will not simply be determined by who can open the most stores or offer the lowest price. It will be shaped by businesses that understand their customers, use data intelligently, invest strategically and build operating models capable of adapting to changing conditions.
Nedbank brings together financial expertise and sector understanding to help businesses navigate that transformation. Supporting a franchise is about more than funding the next store; it’s about understanding the commercial model behind it, identifying where investment can unlock efficiency, helping businesses manage risk and supporting the decisions that enable sustainable growth.